Imagine this scenario for a minute.
You’re funding thousands of loans. Your acquisition channels are working. Your underwriting process is established. Portfolio performance is relatively stable. Nothing is obviously broken.
In fact, you’ve spent years getting the business to this point.
But what if one segment is converting slightly below its potential? What if a verification step is adding a few unnecessary dollars to the cost of every funded loan? What if a decision rule that made perfect sense two years ago is quietly costing you money today?
None of these is a five-alarm fire.
At your volume, it doesn’t have to be.
Because once you’re operating at scale, getting 20% better isn’t necessarily the opportunity sitting in front of you.
Finding the 2% you haven’t noticed might be.
The math of “just a little better”
Let’s put some dollars behind that.
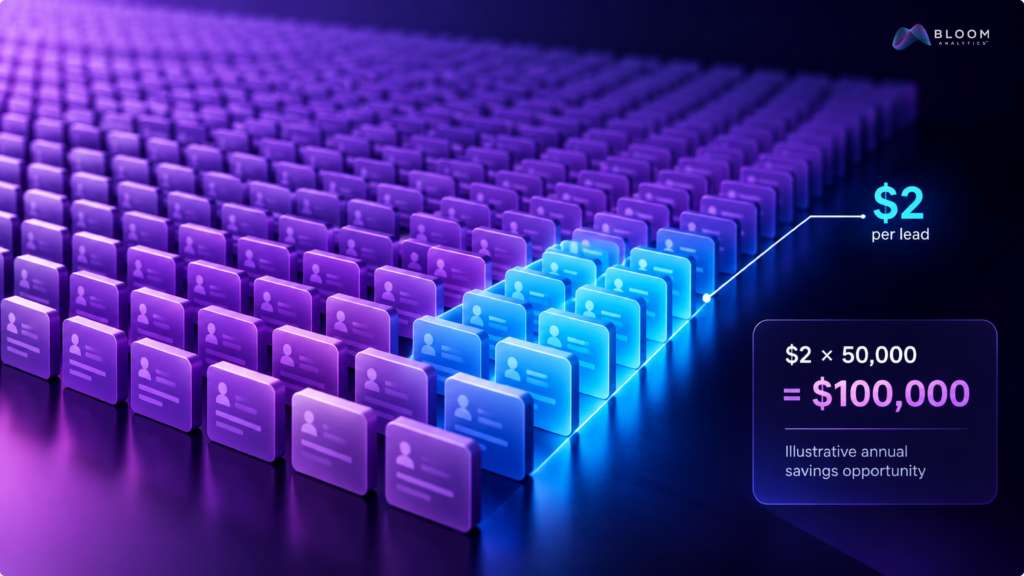
Suppose you’re processing 500,000 leads a year.
Analysis uncovers a segment representing 50,000 of those leads where acquisition costs could potentially be reduced by an average of just $2 per lead without sacrificing the performance you need.
That’s $100,000 a year.
No new product. No sweeping transformation. No 20% performance breakthrough.
Just $2, in one part of an operation that’s already working.
And that’s only one lever.
A little less acquisition waste. A slight improvement in conversion. A small reduction in losses. A process that costs a little less each time it runs.
Individually, none of those may look transformational. But repeated across hundreds of thousands of transactions, decisions or customer interactions, the economics can look very different.
Scale gives small improvements somewhere to compound.
The opportunity isn’t always finding one enormous lever to pull. Sometimes it’s finding several small ones that have been hiding in plain sight.
Your data may know something you don’t
The good news is that at this stage, you have something you didn’t have when you were starting out:
History.
Every lead acquired, decision made, loan funded, payment received and outcome observed adds another piece to the picture.
But having years of data and extracting everything useful from it are two different things.
Some patterns are easy to spot because you’re already looking for them.
Others live in the intersections.
A segment behaves differently under certain conditions. Two groups that appear similar at first produce meaningfully different outcomes later. A source that looks expensive by one measure looks very different when evaluated against another.
The question becomes less:
Do we have enough data?
and more:
What haven’t we thought to ask of it yet?
That’s where deeper analysis can become particularly valuable.
Not because an algorithm magically discovers the answer to every business problem, but because analytics can test assumptions, surface relationships and help you investigate parts of your operation that might otherwise look perfectly ordinary.
Finding the opportunity is only half the problem
Now suppose you’ve found an opportunity.
Maybe it’s that $100,000 opportunity we talked about earlier. Maybe it’s something much larger.
The obvious reaction is: Great. Let’s go get it.
But this is where optimization gets more complicated.
Moving one lever can move several others.
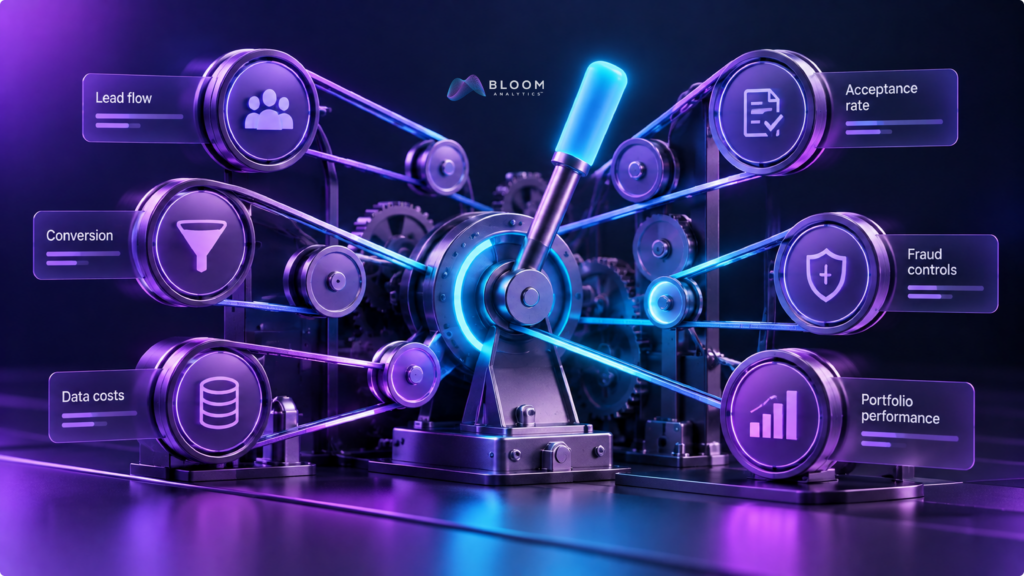
Reduce acceptance rates and you may change lead flow. Increase underwriting activity and your data costs may rise with it. Tighten fraud controls and you may also affect conversion.
In other words, you can successfully move the metric you were targeting and still create an unintended consequence somewhere else.
That’s why finding the opportunity is only part of the job.
You also need to understand what could happen when you act on it.
You’re not simply asking:
Can we move this metric?
You’re asking:
What happens to everything else if we do?
That means looking at the intended result, the potential tradeoffs and the relationships between different parts of the operation before deciding whether an improvement is actually an improvement.
The biggest opportunity may be hiding in something boring
This is perhaps the least glamorous part of running a mature operation.
The next major improvement may not come from launching something new.
It might come from discovering that a process you’ve run thousands of times could work slightly better.
Or that a segment buried inside an aggregate number deserves a second look.
Or that a decision rule that once served the business well hasn’t kept pace with how your portfolio has changed.
These aren’t always exciting discoveries.
But at scale, boring can get expensive.
And it can get profitable, too.
The organizations that keep improving aren’t necessarily the ones constantly rebuilding the machine.
They’re the ones willing to keep opening it up, looking closely at how the pieces are performing and asking whether there’s another adjustment worth making.
Sometimes you don’t need a transformation
At Bloom Analytics, some of the most interesting questions aren’t about building something entirely new.
They’re about understanding what’s already happening in your business.
Where is performance stronger than expected? Where is value being lost? Which assumptions still hold? Which ones deserve to be tested again?
Advanced analytics can help turn years of operational data into a closer look at those questions, giving you evidence you can use to decide where an adjustment is worth making.
But identifying the opportunity isn’t enough.
At Bloom, we also help teams think through how a change may affect other parts of the operation, anticipate potential tradeoffs and plan for what happens next.
Because once you’ve built the machine, the next stage of growth may not require you to move faster.
It may require you to tune it.
You may not need a transformation. You may need a closer look.
Talk to Bloom about advanced analytics and performance tuning.