There's an appealing idea in lead buying: somewhere in the traffic your competitors pass on, there's a pocket of leads they've undervalued, and whoever finds it first gets an edge.
Sometimes that's true. Some buyers who go looking find a real advantage, and others find a story they wanted to be true.
So which is it, hidden opportunity or wishful thinking? The truth is: it depends. It depends on your traffic, your costs, and what your own results show.
Whether you sort your leads with a vendor’s model, one you built in-house, or a combination of scoring tools, once you start hunting for overlooked leads, it makes sense to ask:
Is there a score out there that sees something our process doesn’t?
Disagreement is cheap
If you're competing for the same leads as everyone else, a new score needs to tell you something useful beyond what you already know. So it's natural to hope it will disagree with your existing model in places that matter. It's a hope we've heard from lenders.
But a disagreement proves nothing by itself.
Any two scores can differ on individual leads. Say your current score puts a particular lead in the bottom 20% of your traffic, and a second score puts that same lead in the top 40%. That looks like a find.
Now check what happened to similar leads. If the leads the second score ranked favorably went on to perform like the rest of your bottom 20%, you've found a second opinion and nothing more. If they consistently outperformed that group, you've found something worth investigating.
The same disagreement can mean either, and the scores alone can't tell you which.
Outcomes can.
Where an edge could actually come from
Often it comes from asking a more specific question.
Picture a lender buying leads from several sources. An overall quality score ranks two groups of leads about the same, but their history tells different stories. One group converts more often but has higher first-payment default. The other converts less often but performs better after funding.
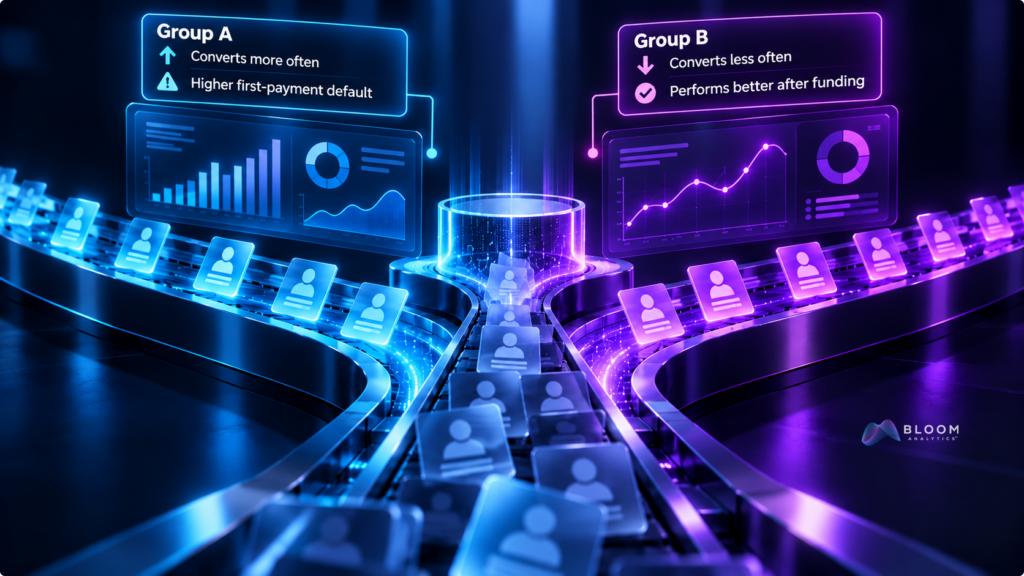
Which is the better buy depends on what you're optimizing for and what each group costs. A lender focused on volume may prefer the first group, and one trying to reduce early defaults may prefer the second. A single overall score can blur that difference, while scores built for a specific outcome, like conversion or first-payment default, can separate it.
So a second score has a good reason to disagree with your current process when it measures something your current process blurs. How much that matters depends on your traffic, your goals, and what your history shows. Which raises a practical question: where do you look first?
The "no" pile isn't one pile
The best place to start may be the traffic you’re already passing on. Suppose a lead provider offers you 50,000 leads, and your current process says only 15,000 are worth buying. What about the other 35,000?
You may be right to pass on all of them. But those leads might not be as alike as they look.
Imagine using an additional score to divide the 35,000 into five quality tiers. The weakest tiers may confirm your decision, and that’s a useful result. But one tier might resemble the purchased leads that have performed best.
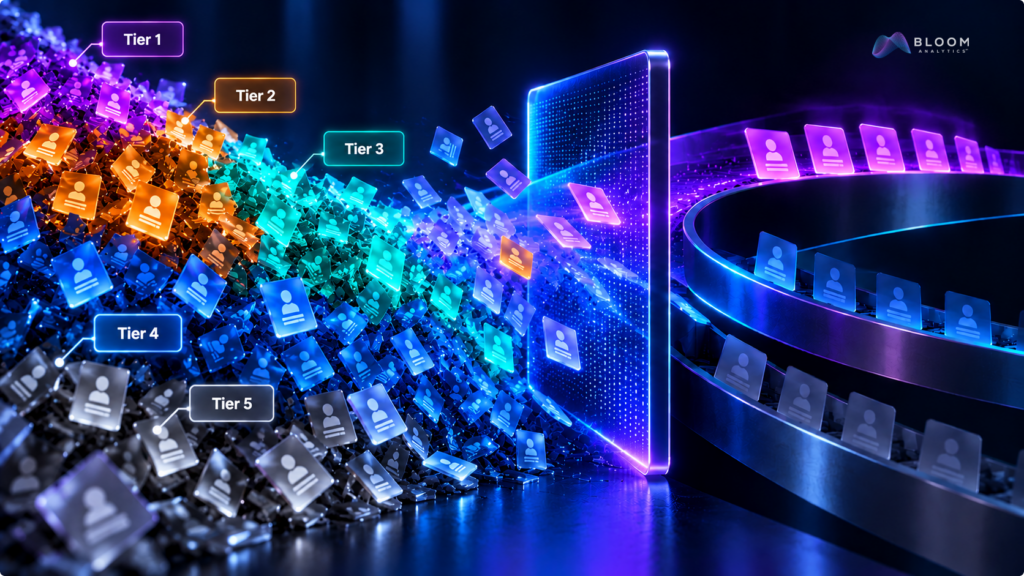
You haven’t discovered that 35,000 leads are secretly valuable. You’ve found a smaller segment that might deserve a different bid, a different route, or a small test buy. Which raises an obvious question: if that segment is worth buying, why isn’t everyone buying it?
Ask why everyone else passed
Sometimes the answer is that they’re missing something. More often, other buyers pass for reasons: price, fraud exposure, product fit, compliance appetite. Some won’t apply to you, which is the whole premise. Others will, and it’s worth knowing which. Even a real pocket gets bid up once enough buyers notice it.
The question to ask is whether the traffic is better enough, at your price, at your volume, for your product.
Answering that takes data, and that’s where it gets tricky.
You can only grade what you bought
Here's the part vendor content usually skips. The leads you passed on generally have no outcomes in your portfolio, so any pocket you find among them is a hypothesis.
The way through is to start with what you do know. Score the leads you purchased and compare the scores against what actually happened. If the scores meaningfully separate stronger-performing leads from weaker ones, that's encouraging evidence, though it doesn't prove the same patterns will hold among leads you didn't buy. Then score the traffic you passed on to see whether any segments warrant a closer look.
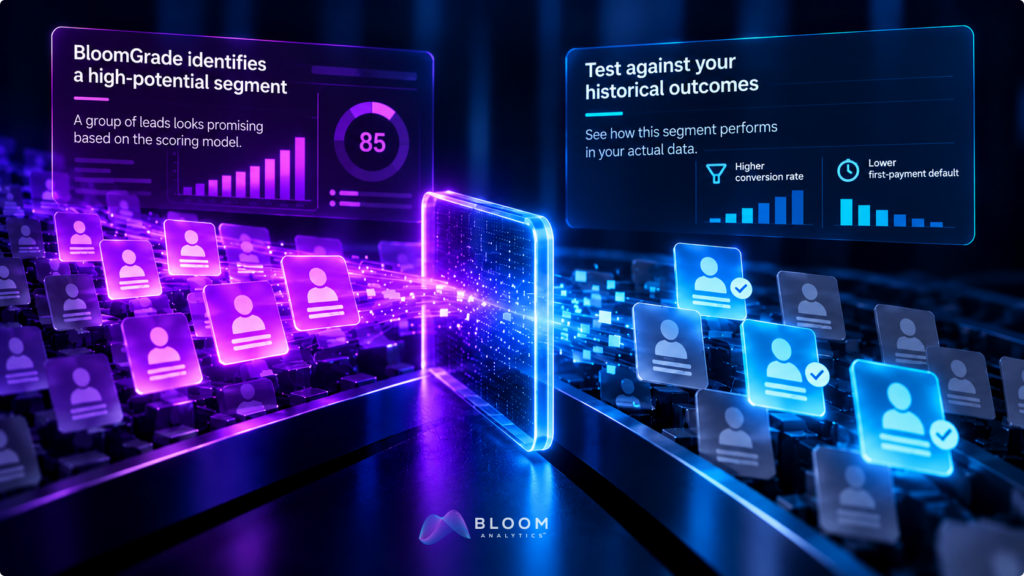
Treat your first purchase from a previously rejected tier as an experiment: small, controlled, and evaluated on data that wasn't used to identify the opportunity in the first place. Slice 35,000 leads enough ways and some tier will look brilliant by luck.
Put it to the test
You can explore this approach with different scoring tools. If you'd like to test ours, here's how it works.
BloomGrade is a suite of lead scores: an overall lead quality score, plus specialized scores for outcomes such as conversion and first-payment default. In a complimentary data study, we apply BloomGrade scores to your historical lead data so you can examine the quality tiers and compare them against what actually happened.
That gives you a way to evaluate which signals are useful for your lead-buying strategy and whether further testing makes sense.
Performance data is up to you, and so is the timing. We can score your leads without it and you can run the comparison yourself, or you can share it and we'll put the comparison together for you. If you're early enough that you don't have much history yet, you can still start with the scores and compare as results come in. Either way, we don't use your performance data to build or tune the scores. They're built independently, and your results are the answer key, because we'd rather you check our work than take our word for it.
We're not claiming the leads other lenders reject are secretly good. We're offering another way to decide whether any of that traffic is worth a second look. And the real test of a scoring model is whether its differences hold up on your own portfolio.